

Most IFA firms are unlikely to apply for permission to offer targeted support. The firms that have announced the permission so far are large pension and investment providers, a wealth manager and a bank.
It can still reach you, though. Six months in, providers that hold many of your clients' pensions are rolling out FCA targeted support. Some of the people it prompts may want an adviser. And some of your own clients may forward a suggestion and ask what to do.
Targeted support can affect firms that never apply for it. Here's what has happened, what it can mean for an advice firm, and four questions to settle before the year end.
What FCA targeted support is
Targeted support lets an authorised firm make ready-made suggestions to groups of consumers who share common characteristics: people with £10,000 or more in cash savings, for instance. In the FCA's words, consumers "will receive recommendations, but they will not be based on a full, in-depth individual assessment" (FCA, December 2025). It sits between generic guidance and a personal recommendation.
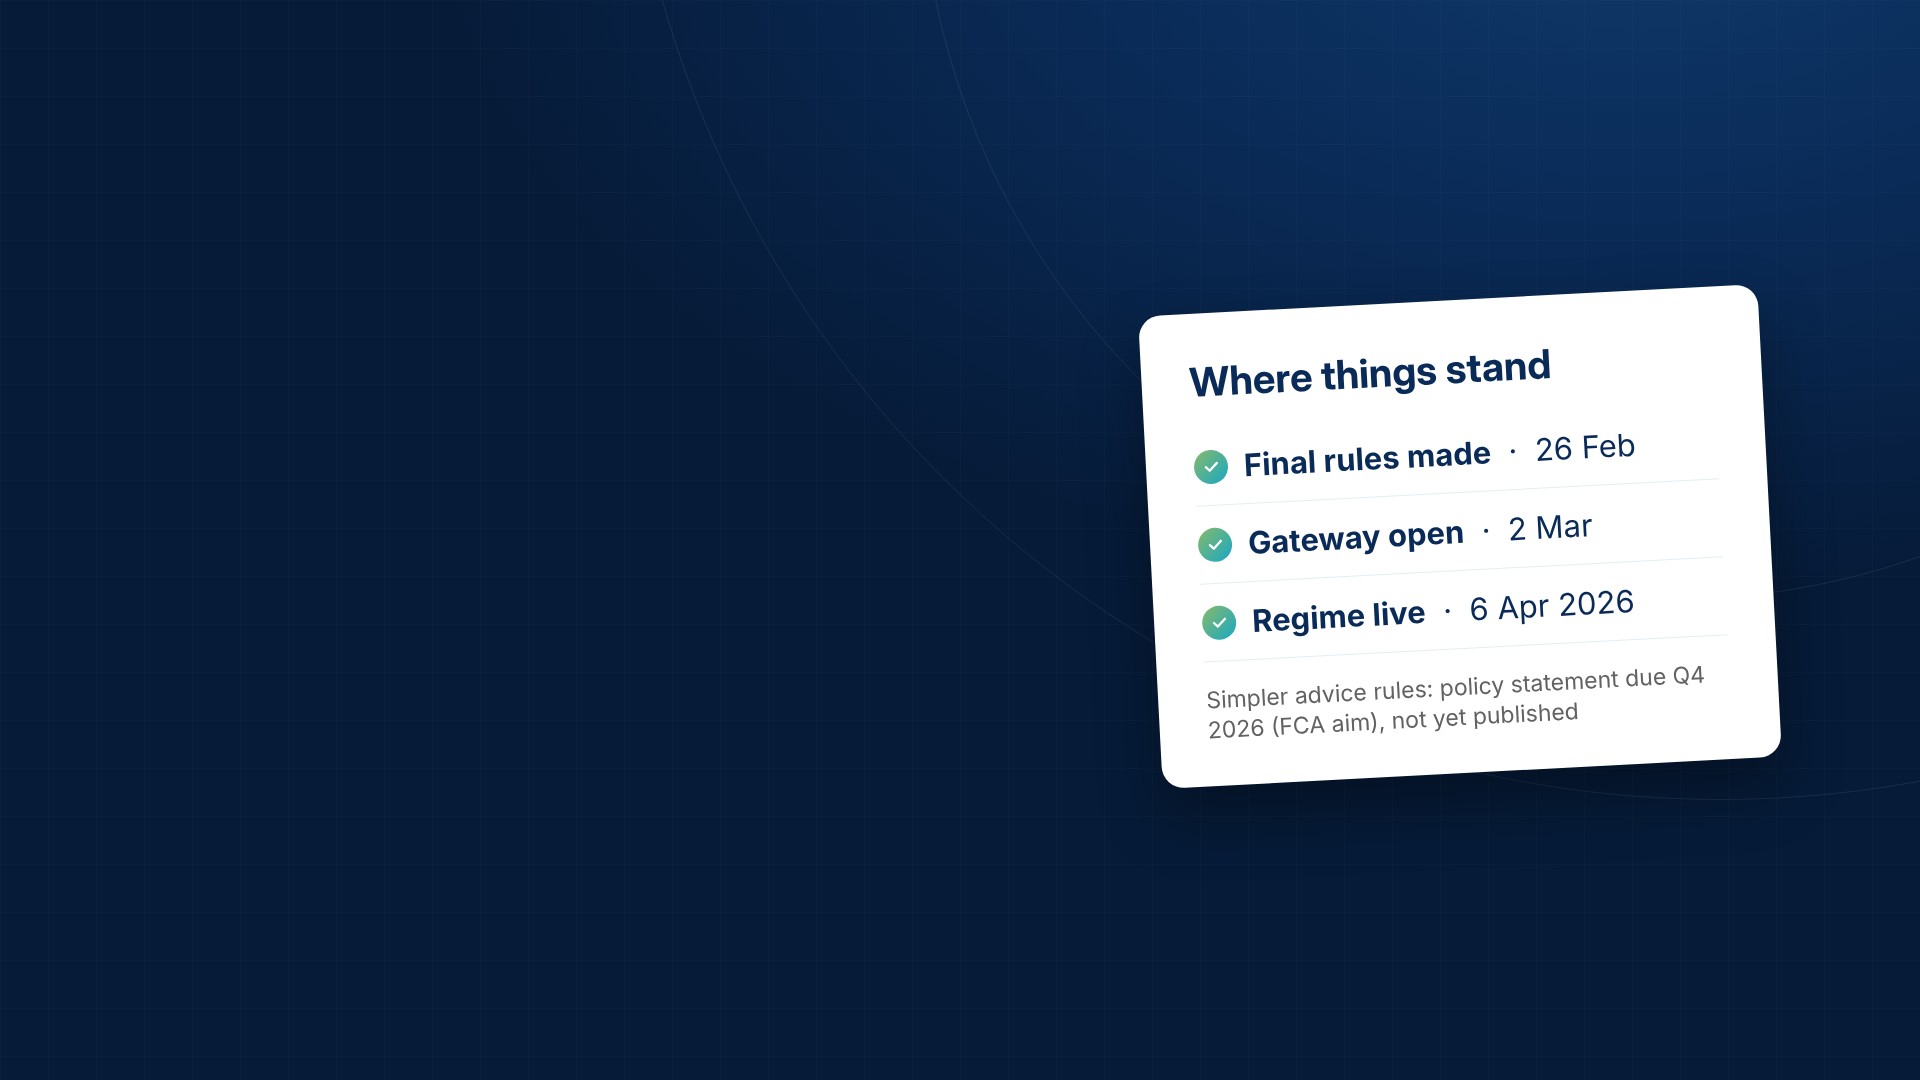
How the regime got going:
- 26 February 2026: the FCA Board made the final rules (PS25/22).
- 2 March 2026: the application gateway opened.
- 6 April 2026: the regime went live.
Several firms have announced that they hold the permission. Three of them:
- Royal London was among the first through the gateway (approved 2 April) and on 20 April launched a Targeted Support ISA service for its app customers.
- Legal & General announced its approval on 1 May, starting with workplace pension members whose savings are fully invested in cash.
- Aviva announced its approval on 17 June and said it would launch in phases from summer 2026, pension customers first.
How it reaches an advice firm
The first announced approvals went to providers, which hold the customer data that defines a group and have millions of customers.
Advisers might read that as competition. The FCA's figures show who it is aimed at:
- Around 23 million consumers are underserved by the markets for advice and guidance (FCA, March 2026).
- At least 18 million people could be offered extra help with their investments and pensions over the next decade (FCA, December 2025).
- Around 7 million UK adults have £10,000 or more in cash savings (FCA, December 2025, same release).
- Fewer than one in ten people get regulated financial advice (FCA, December 2025, same release).
On those figures, most of the people targeted support reaches have no adviser today.
It can still reach advice firms, in two ways. Expectations first. When a provider's suggestion lands on a client's phone and can be acted on in the app, the client may compare it with your annual review letter.
Then there's demand. A group-level suggestion can't deal with an inheritance or a retirement with five moving parts. Some people may realise they need more.
Picture someone with a £60,000 pension pot whose provider's suggestion has sent them looking for full advice. Can your firm take them on and make money doing it? First, that's a question about your cost to serve. Our guide to bridging the advice gap profitably covers the same question.
When a client asks "should I do this?"
Some suggestions may reach your existing clients. A targeted support suggestion is designed for a group; a personal recommendation is designed for a person. If a client forwards a suggestion and you tell them whether to act on it, based on their circumstances, that can be a personal recommendation. A personal recommendation needs up-to-date information about the client and a suitability assessment, whether or not you charge for it. Decide now how you'll handle these requests, and whether you'll charge, because the first one can arrive by email.
Simpler advice rules are next
In March 2026 the FCA published CP26/10, consulting on simpler suitability rules and more flexible ongoing advice. Two proposals touch almost every advice firm:
- Replacing the annual suitability review with a frequency based on each client's needs and circumstances (para 3.14).
- Suitability reports that include only useful, relevant information, with length proportionate to the recommendation (paras 1.10 and 2.53).
The consultation closed on 22 May. The FCA said it aimed to publish a policy statement in Q4 2026 (para 1.25). As of 30 October, nothing has been published.
Targeted support and CP26/10 both come from the FCA's Advice Guidance Boundary Review: targeted support adds help between guidance and advice, and CP26/10 simplifies the rules for full advice.
Four questions for firm owners before the year end
Put these on the agenda of whoever runs the firm, or work through them yourself if that's you.
- Where do we stand? Agree the firm's position on targeted support and the reasons for it. "Not for us" is one answer; record the reasons.
- What will our clients receive? Many hold workplace pensions and old plans you don't advise on. Ask your provider contacts whether advised customers are excluded from their groups. Until you know, don't assume clients' workplace schemes and old personal pensions will be left out. That way the first you hear of a suggestion isn't from a client holding one.
- What does it cost us to say yes? Add up the hours a new client takes in year one and cost them at your hourly rate. Then find the portfolio size where your fees cover it. Below that line, a new client loses you money.
- Are we ready for simpler advice rules? If the final rules land close to the proposals, which clients' annual reviews might not need to be annual? And does your process record why?
If time's short, start with question 3. Your answer is the smallest client your firm can take on without losing money.
What to do next
Five steps turn those answers into actions:
- Email your main provider contacts this week and ask whether advised customers are excluded from their targeted support groups.
- Agree a one-line rule for forwarded suggestions: who replies, how, and whether you charge.
- Work out your minimum profitable portfolio size and share it with whoever handles new enquiries.
- List the clients whose annual review might not need to be annual, so the work is ready if the rules change.
- Check the FCA's CP26/10 page each month until the policy statement is out.
Whatever you decide, write it down. A recorded position is easier to defend to a client or a buyer than a shrug.
On JustFA
Saying yes to a new client means a fact-find, a recommendation, implementation and, later, reviews. Here's how firms using JustFA handle that work. Clients complete the fact-find online and the adviser reviews it. In JustFA 2.0, the adviser builds the recommendation from the fact-find data on one screen and checks the document pack generated from the firm's templates. Clients then sign in one guided flow, and implementation follows automatically once signed. Each later review starts from a fact-find pre-filled from the last one.
Where this leaves advisers
On the FCA's figures, most of the people targeted support reaches have no adviser today. Someone fresh from a phone suggestion may expect your firm's first steps to move as fast.
Taking on people who want full advice needs no new permission. Whether it pays depends on your cost to serve.
Common questions
What is FCA targeted support?
Targeted support is a new kind of help the FCA regulates, live since 6 April 2026. It lets authorised firms make ready-made suggestions to groups of consumers who share common characteristics, such as having £10,000 or more in cash savings. It sits between generic guidance and a personal recommendation: the FCA describes the output as recommendations that are not based on a full individual assessment.
Which firms have targeted support permission in 2026?
Among the large providers, Royal London received regulatory approval on 2 April 2026 and launched a Targeted Support ISA service for its app customers on 20 April. Legal & General announced its approval on 1 May, with workplace pension members whose savings are fully in cash as its first use. Aviva announced on 17 June that it would roll out in phases from summer 2026, pension customers first. Other firms also hold the permission, through the FCA gateway that opened on 2 March 2026.
Do financial advisers need a new permission for targeted support?
Only if the firm wants to offer it. Targeted support needs its own FCA permission; a firm that keeps giving personal recommendations needs nothing new. Most IFA firms are unlikely to apply: the firms that have announced the permission so far are large pension and investment providers, a wealth manager and a bank.
Can replying to a forwarded targeted support suggestion be a personal recommendation?
Yes, it can. A targeted support suggestion is designed for a group of people. If an adviser tells the client whether to act on it, based on that client's own circumstances, that can be a personal recommendation. A personal recommendation needs up-to-date information about the client and a suitability assessment, whether or not the firm charges for it. A firm can settle in advance who replies to these requests, how, and whether the work is charged.
What is CP26/10 and how is it different from targeted support?
CP26/10 is the FCA's consultation on simpler rules for personal advice, published in March 2026 and closed in May 2026. It proposed suitability reports that contain only useful, relevant information, and review frequency based on client need. The FCA said it aimed to publish a policy statement in Q4 2026. As of 30 October 2026, that policy statement had not been published. Targeted support is different: it is live, and it provides suggestions designed for groups of consumers without a personal recommendation.
JustFA
See how JustFA works
JustFA runs the adviser back office, the investment platform and the client portal as one system. It is used by 50+ UK advisory firms, with no setup fee and a standard four-week go-live.